
contact
Our CFP® professionals are ready to help.
Not sure where to start? Check our frequently asked questions below, or reach out directly to one of our advisors.
-
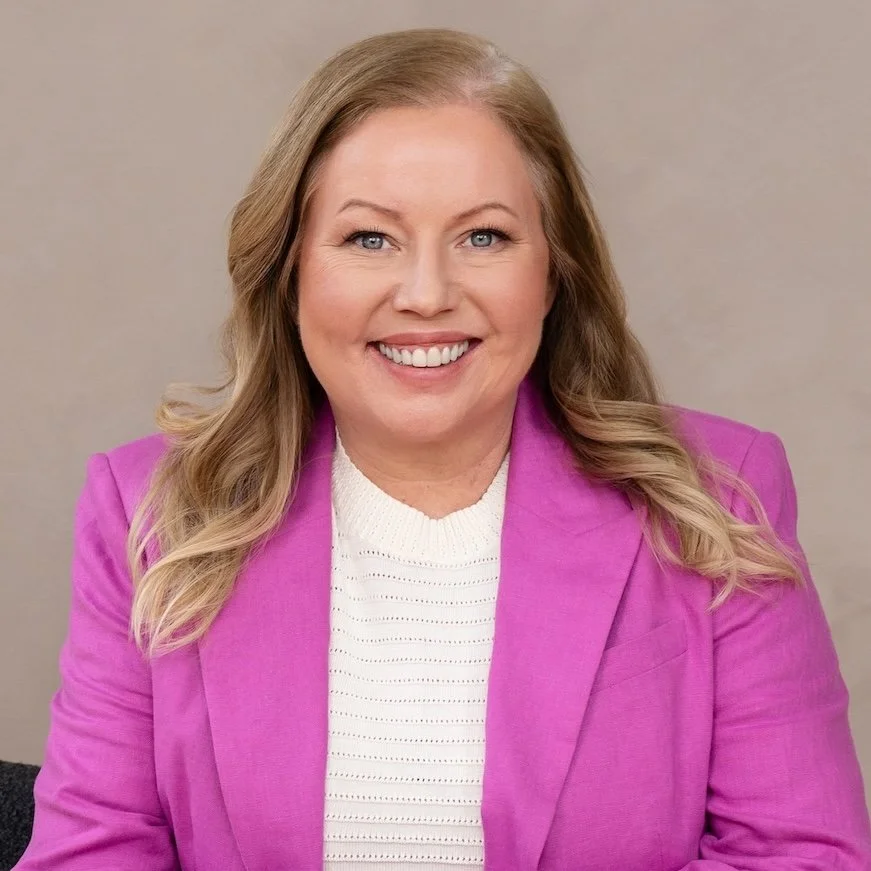
Melissa Joy, CFP®
-
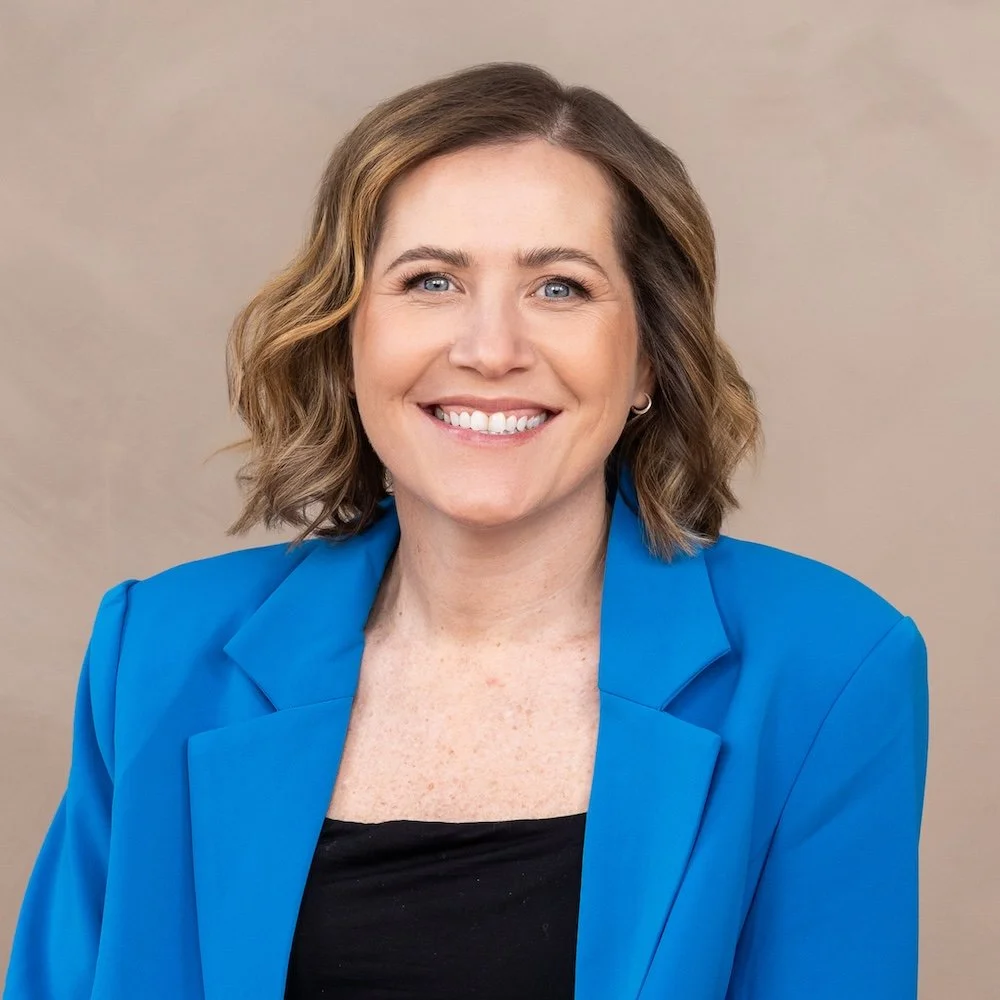
Alexa Kane, CFP®
-
Toni Wander, CPA, CFP®, CIMA®, CSRIC®
common questions
Frequently asked questions
-
A financial planner helps you make decisions about your money in the context of the life you want to live. Managing investments is part of that work, but financial planning goes further. It can include setting goals, managing cash flow, preparing for retirement, planning for taxes, reviewing insurance, coordinating estate plans, and saving for a child’s education.
At Pearl Planning, we look at how these pieces fit together. We help you understand your options, make informed decisions, and adjust your plan as your life changes. Our work starts with your finances, but it’s guided by what matters to you.
-
Financial planning helps you understand where you stand, where you want to go, and the decisions that could help you get there. Wealth management puts that plan into action and keeps it moving as your life changes.
At Pearl Planning, wealth management includes managing investments, but it also means helping you use and grow your financial resources to support your needs, goals, and the people who matter to you. A financial plan can serve as a guide. Wealth management is the ongoing work of making decisions, taking action, and adjusting course over time.
We also work hard to provide additional services beyond investments and financial planning software. We have high yield savings options, tax aware investing strategies, we can introduce you to experience professionals to help you with things we don’t cover, and more.
-
The terms financial planner and financial advisor are often used interchangeably. A title alone may not tell you what kind of advice you’ll receive.
At Pearl Planning, we call ourselves financial planners because we believe the value of advice goes well beyond investments. Some of our most important conversations aren’t about an account at all. They’re about what matters to you, where life feels complicated, and how your experiences with money shape the decisions you make. That work goes much further than recommending what to buy or sell.
We believe financial planners should put their clients’ interests first. We also encourage people to look at an advisor’s credentials and the standards behind them. For us, the Certified Financial Planner™ certification provides an important foundation for the planning work we do.
-
A CFP® professional has met requirements for education, a comprehensive exam, financial planning experience, and ethics. Their training covers areas such as investments, retirement, taxes, insurance, estate planning, and cash flow. Earning the certification takes more than passing a test: CFP® professionals must also complete continuing education and follow CFP Board’s ethical standards, including a duty to act in a client’s best interests when providing financial advice.
Why does that matter? Your financial decisions rarely fit into just one category. We believe the CFP® certification provides a strong foundation for advice that considers the full picture of your life and finances.
Our three most senior financial planners are all CFPs and three associate advisor team members are at various stages working toward the certification. It reflects the knowledge and standard of care we value in the people serving our clients.
-
A fiduciary is an advisor who must act in your best interests when giving advice. That means taking the time to understand your circumstances, recommending a course of action that fits your needs, and addressing conflicts that could affect the advice you receive.
At Pearl Planning, this responsibility applies in two ways. As an SEC-registered investment adviser, our firm owes clients a fiduciary duty. Our CFP® professionals also have a fiduciary duty under CFP Board’s standards whenever they provide financial advice.
Why does it matter? You deserve to know whose interests are guiding a recommendation, especially when the decision affects your future. Being a fiduciary does not mean an advisor has no conflicts or can guarantee a result. It means your interests must come first, and conflicts must be addressed. We believe that is the right foundation for a planning relationship.
-
The cost depends on the advisor and how they’re paid. Some charge a flat or hourly fee, some charge a percentage of the investments they manage, and others receive commissions connected to products you purchase. Before working with an advisor, you should understand both what you’ll pay and how they’re compensated.
At Pearl Planning, our cost is based on the assets we manage for you. That fee includes our investment management and comprehensive financial planning services. We use a published fee schedule so you can see how our advisory fee is calculated based on the assets that we manage on your behalf.
There also may be costs for the investments that you own – these can be expense ratios or management fees. We believe you should be able to see and understand the full cost of the advice and investments you receive and we welcome conversations and discussions about your costs both when establishing an advisory relationship and over time.
-
Start with questions that show you how the relationship will work in real life:
How are you and your firm paid? What fees and other costs will I pay?
What does your planning process look like? What help will I receive after the initial plan is finished?
Who will I work with? Who makes recommendations, who handles follow-through, and which decisions remain mine?
What is your approach to investing and financial advice? How would you adapt it to my goals and circumstances?
What experience do you have with people facing decisions like mine? Can you give me an example of how you’ve helped?
What happens when life gets difficult? How can I reach you, and what kind of support can I expect?
You can also check an advisor’s registration and disciplinary history through Investor.gov’s background check.
Then pay attention to the conversation itself. Do they listen? Can you ask a question without feeling embarrassed? Financial planning often involves personal and difficult decisions. You should feel comfortable being honest with the person helping you make them.
-
We’re biased: we think many people can benefit from a financial planner. We also know that some people enjoy managing their own money and feel confident doing it. The question is whether your approach is still working for you.
It may be time to talk with a planner if you’re unsure how a strategy works, cash is piling up because you don’t know what to do with it, or important financial tasks keep slipping down your to-do list. You might also find that decisions that once felt simple have become more connected and complicated.
Managing your own money takes time, attention, and a clear sense of what you’re trying to accomplish. If you enjoy the work and are getting things done, you may be comfortable continuing on your own. If you’re wondering whether you’re missing something or would value help putting decisions into action, a conversation with a CFP® professional could be a useful next step.
-
It may be time to consider a change if you meet with your advisor occasionally but only talk about investments. Your accounts matter, but your advisor should also understand what you want your money to make possible, whether that’s retiring early, supporting family, or navigating a change in your life.
Another sign is feeling that your goals aren’t being explored. If you want to retire earlier than expected and the conversation stops at “wait until traditional retirement age,” you may want an advisor who will help you examine the options. Or perhaps the advisor you trusted has retired, and the person who took over doesn’t seem to know you.
A second opinion can help you decide. When someone considers working with Pearl Planning, we review their existing accounts and discuss the other areas of their financial life that may need attention. That gives them a clearer picture of the service they’re receiving, what they might need, and what it would cost to work with us. Sometimes a different level of service is available for a similar cost. The right choice depends on what matters to you and the value you’re getting.